The Hidden Cost Most Business Owners Never Calculate
Many business owners spend hours negotiating lower credit card processing rates.
They'll compare processors to save a few tenths of a percent on processing fees, yet routinely give customers 30, 60, or even 90 days to pay an invoice without ever calculating what that delay actually costs.
The truth is that extending payment terms can often cost more than accepting a credit card.
If your business invoices customers, one question deserves serious consideration:
What is the real cost of waiting to get paid?
---
Why This Matters for Pennsylvania Businesses
Whether you're a contractor in Philadelphia, an auto repair shop in King of Prussia, a landscaper in Chester County, a medical office in Delaware County, or a retailer on the Main Line, cash flow is what keeps your business moving.
At Custom Payments LLC, we help businesses throughout Pennsylvania, New Jersey, Delaware, and Maryland improve cash flow with customized merchant services, online invoicing, ACH payments, recurring billing, POS systems, and next-day funding solutions.
Our goal isn't simply to lower your processing costs—it's to help you get paid faster, strengthen your cash flow, and free up working capital so you can grow your business.
---
Every Invoice Is a Loan
When you offer Net 30 terms, you're essentially lending your customer money for 30 days.
Net 60? You're financing their business for two months.
Net 90? You're acting like their bank—for three months—without charging interest.
Meanwhile, your expenses don't stop. You still have to pay employees, rent, insurance, taxes, inventory, fuel, utilities, equipment payments, and marketing expenses. Your vendors expect payment even though your customer hasn't paid you yet.
---
When Do You Actually Get Paid?
The chart below illustrates the difference between accepting electronic payment and sending a Net 60 invoice on a $20,000 project.
!Payment Timeline: Net 60 Invoice vs. Electronic Payment on a $20,000 Project
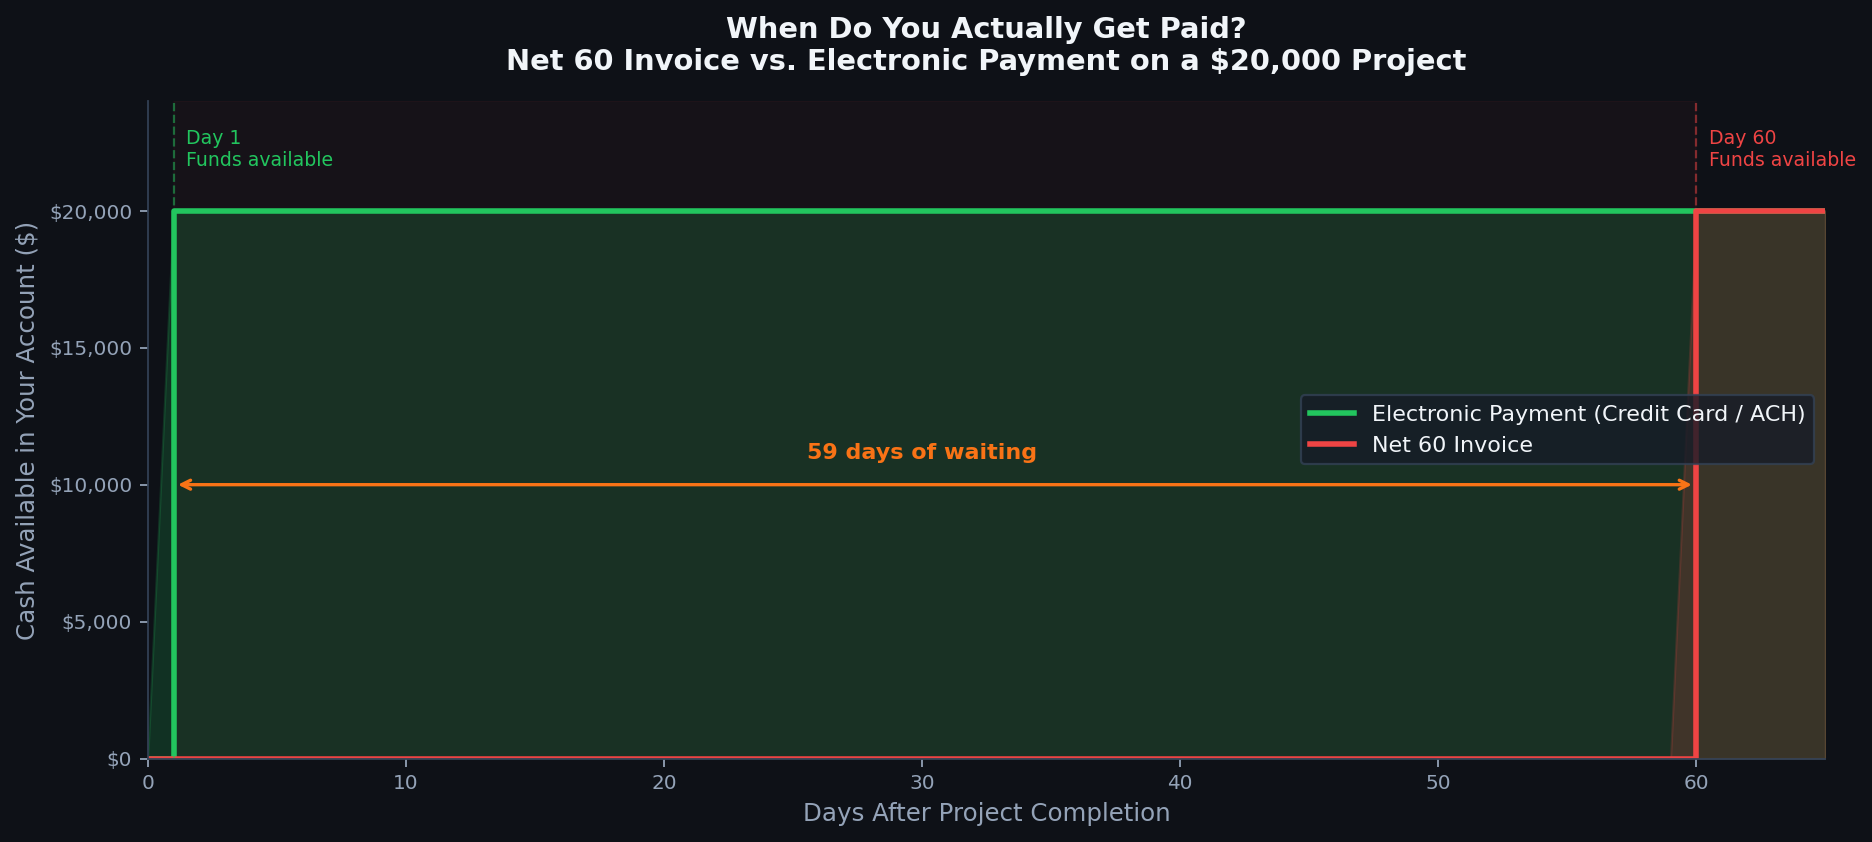
Hypothetical example for illustration purposes. Actual funding timelines vary by processor, merchant eligibility, and payment method.
With electronic payment, funds are often available by the next business day. With a Net 60 invoice, your cash remains unavailable for up to two months—while your expenses continue.
---
The Hidden Cost of Accounts Receivable
Many business owners think: "There's no processing fee if they mail me a check."
Technically that's true. But there are numerous hidden costs that rarely appear on a financial statement.
Outstanding invoices often create:
- Reduced cash flow
- Delayed hiring
- Slower inventory purchases
- Lost opportunities
- Borrowing against a line of credit
- Interest expense
- Administrative time collecting invoices
- Late-payment risk
- Bad debt write-offs
- Cash flow uncertainty
These costs can easily exceed what you would have paid to accept a credit card or ACH payment.
---
What's Your Accounts Receivable Really Costing You?
Most business owners know how much they pay in credit card processing fees. Far fewer know how much they're losing by waiting to collect payment.
The chart below shows hypothetical hidden costs for a business carrying $50,000 in Net 60 accounts receivable.
!Hidden Annual Cost of Carrying $50,000 in Net 60 Accounts Receivable
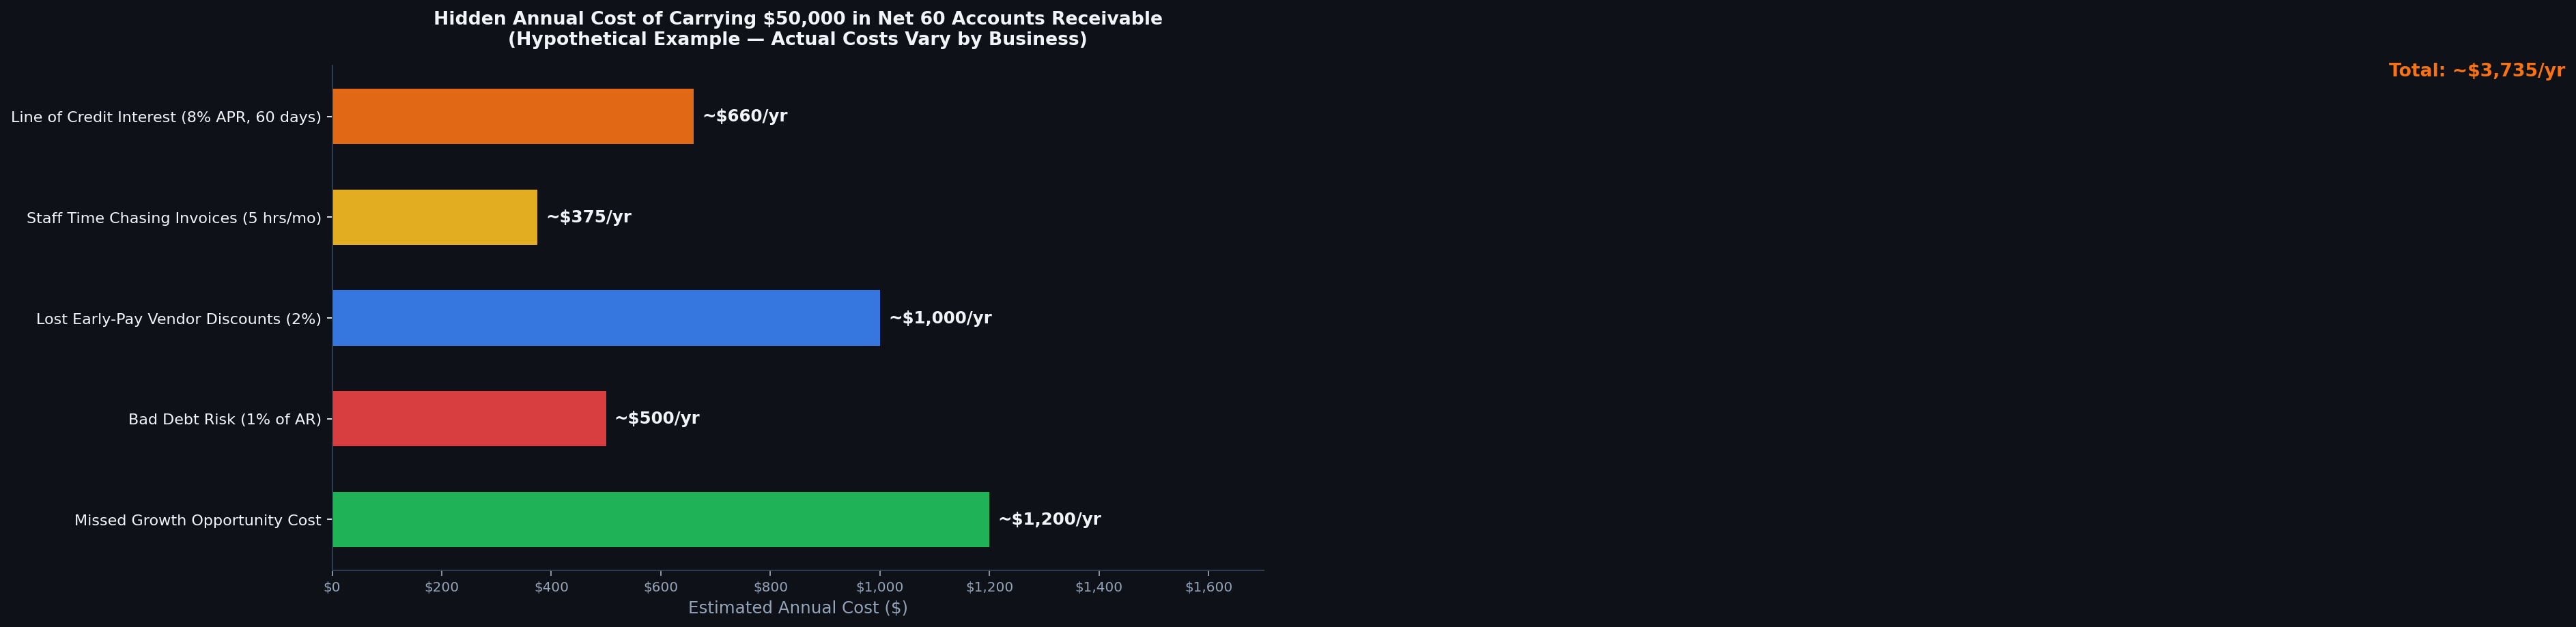
Hypothetical example only. Actual costs vary significantly by business, industry, interest rates, and staffing. These figures are for illustrative purposes and should not be relied upon as financial projections.
Take a few minutes to estimate the hidden cost of your outstanding invoices:
Step 1: Add Up Your Average Accounts Receivable
What's the average amount of unpaid customer invoices you carry each month? ($10,000 / $25,000 / $50,000 / $100,000+)
Step 2: How Long Does It Take to Get Paid?
On average, how many days pass before your customers pay? (Less than 15 days / 15–30 days / 31–60 days / 61–90 days / More than 90 days)
Step 3: Answer These Questions
While you're waiting to get paid…
- Have you ever used a business line of credit?
- Have you postponed purchasing equipment?
- Delayed hiring an employee?
- Waited to buy inventory?
- Missed an opportunity because cash wasn't available?
- Spent time sending payment reminders?
- Wondered whether a customer would pay on time?
If you answered "Yes" to any of these questions, your accounts receivable is costing your business more than you may realize.
---
The Hidden Expenses Most Owners Never Calculate
Outstanding invoices often create costs that don't appear as a line item on your financial statements, including:
- Interest paid on business loans or lines of credit
- Employee time spent creating invoices and collecting payments
- Administrative costs for statements, reminder emails, and phone calls
- Cash tied up instead of being invested back into your business
- Delayed growth opportunities
- Increased risk of late payments or bad debt
- Reduced financial flexibility during slow periods
Even if these costs are difficult to measure precisely, they have a real impact on profitability.
---
12-Month Cash Flow Comparison
The chart below shows how cumulative cash received compares over 12 months for a business doing $20,000/month in sales—comparing electronic payments (after a hypothetical 2.5% processing fee) to Net 60 invoicing.
!12-Month Cumulative Cash Flow: Electronic Payments vs. Net 60 Invoicing
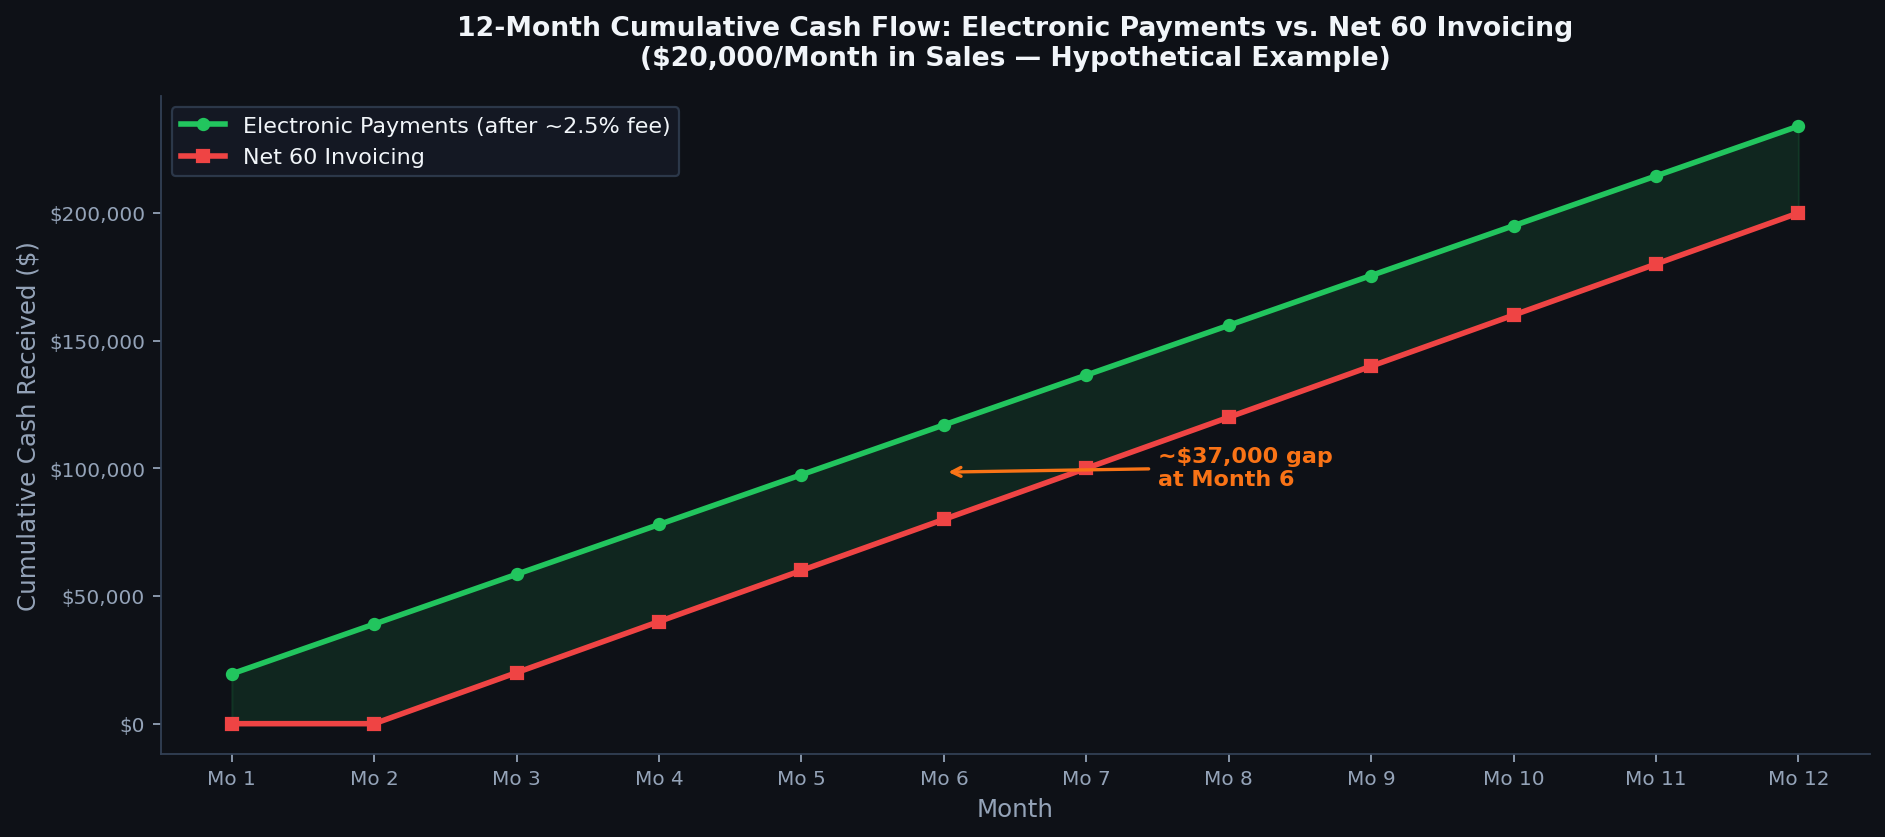
Hypothetical example. Actual processing fees, funding timelines, and cash flow results vary by business and processor. This chart is for illustrative purposes only.
The gap at Month 6 in this example is approximately $37,000—money that could be used for payroll, inventory, marketing, or expansion, but instead remains uncollected.
---
Compare That to Getting Paid Today
Option A – Invoice with Net 60
You wait up to two months to receive payment. During that time, your cash remains unavailable for payroll, inventory, marketing, or expansion.
Option B – Customer Pays Electronically
Your customer pays by credit card or ACH before leaving your office or through a secure online payment link. Funds are deposited quickly—often by the next business day for qualified merchants.
You can immediately pay vendors on time, purchase inventory, invest in advertising, reduce borrowing, strengthen your cash reserves, and take advantage of business opportunities.
---
Your Customer Is Using Your Money
Think about it from your customer's perspective.
If they owe you $15,000 and have 60 days to pay, that $15,000 remains in their bank account—not yours. They're earning the benefit of keeping that cash available.
Meanwhile, you may be using your operating cash, borrowing money, delaying investments, or passing on opportunities.
You are financing their cash flow.
---
Time Is Money
Many businesses focus on percentages. Instead, ask yourself:
- How much is my time worth?
- How much time does my staff spend chasing invoices?
- How many reminder emails are sent?
- How many collection phone calls are made?
- How much stress comes from wondering whether customers will pay?
Every hour spent collecting payments is an hour that isn't generating new business.
---
Faster Payments Create Better Businesses
Businesses with stronger cash flow are often able to:
- Hire employees sooner
- Invest in marketing
- Purchase equipment
- Buy inventory before prices increase
- Handle unexpected emergencies
- Expand into new markets
- Build financial reserves
Cash flow creates opportunity. Waiting to get paid limits it.
---
Give Customers More Ways to Pay
Today's customers expect convenient payment options. Many prefer credit cards, ACH bank transfers, online payment links, digital invoices, and recurring automatic payments.
The easier it is to pay, the faster many invoices are collected. Modern payment systems also reduce administrative work while improving the customer experience.
---
It's Not About the Cheapest Processing Rate
The cheapest processor isn't always the most profitable choice.
Instead of asking, "What's your processing rate?" ask:
- How quickly do I receive my money?
- Can customers pay online?
- Can invoices include secure payment links?
- Do you offer recurring billing?
- Do you support ACH payments?
- Is next-day funding available?
- Will someone local answer my questions?
Sometimes improving cash flow has a far greater impact than reducing your processing rate by a fraction of a percent.
---
One Final Question
If someone offered to put your money in your bank account today instead of 30, 60, or 90 days from now—what would that be worth to your business?
For many companies, the answer is far more than the cost of accepting a credit card.
Instead of asking, "How much does it cost to accept a credit card?" ask yourself, "How much is waiting to get paid costing my business?"
That single question can completely change how you view payment processing.
---
How Custom Payments LLC Helps Businesses Improve Cash Flow
At Custom Payments LLC, we believe merchant services should do far more than process credit cards.
We help businesses improve the entire payment process by offering:
- Customized merchant service plans
- Credit card processing
- ACH payment solutions
- Secure online invoicing
- Email payment links
- Recurring billing
- POS systems
- Virtual terminals
- Mobile payment solutions
- Next-day funding for qualified merchants
- Cash discount and dual pricing programs where appropriate
- Local, in-person support throughout Pennsylvania, New Jersey, Delaware, and Maryland
Instead of calling an 800 number, you'll work directly with a local representative who understands your business and is available when you need assistance.
Whether you're looking to lower your processing costs, speed up collections, or improve your cash flow, we'll customize a payment solution that fits your business—not force you into a one-size-fits-all program.
---
Frequently Asked Questions
Is it cheaper to invoice customers than accept credit cards?
Not necessarily. While invoicing may avoid a processing fee, delayed payments can create financing costs, collection expenses, lost opportunities, and cash flow challenges that outweigh the savings.
Should every business eliminate Net 30 terms?
No. Many industries rely on payment terms to remain competitive. However, every business should understand the true cost of extending credit and look for ways to accelerate collections whenever possible.
Can customers pay invoices online?
Yes. Secure online invoices with payment links allow customers to pay by credit card or ACH, making it easier for customers to pay and helping businesses receive funds faster.
How quickly can I receive my money?
Many merchants qualify for next-day funding, with same-day funding available in certain situations depending on eligibility and processing schedules.
Can Custom Payments LLC help lower payment costs?
Absolutely. We review your current processing setup, payment methods, funding speed, and payment workflows to identify opportunities to reduce costs, improve cash flow, and simplify how your business gets paid.
---
Improve Your Cash Flow—Not Just Your Processing Rate
Most payment processors compete on price alone.
Custom Payments LLC helps businesses improve the way they get paid. We focus on increasing cash flow, reducing unnecessary payment costs, accelerating collections, and providing local, in-person support you simply won't get from an 800-number processor.
If your business is waiting 30, 60, or 90 days to collect invoices—or you're paying more than necessary for credit card processing—let us perform a FREE Payment Processing & Cash Flow Review.
We'll evaluate your current payment process, identify opportunities to improve cash flow, and recommend customized solutions designed specifically for your business.
Whether you're located in Philadelphia, Devon, Wayne, Malvern, King of Prussia, West Chester, Exton, Media, Conshohocken, Lancaster, Reading, Allentown, or anywhere in Pennsylvania, New Jersey, Delaware, or Maryland, we're ready to help.
Schedule Your Free Review Today
Custom Payments LLC — Local. Responsive. Customized Merchant Services.
📞 484-393-1576 | custompayments.biz
Helping businesses reduce payment costs, improve cash flow, and receive the personalized support they deserve—without calling an 800 number.